Tuesday, March 4, 2014

CANFIN HOMES - UPDATE

Canfin Homes earlier recommended @ Rs.145 hits its life time high today @ Rs.195 . This is one stock suitable for low risk takers and still recommending to HOLD it for long term

Old Posting HERE

Saturday, March 1, 2014

SMS PHARMACEUTICALS LTD - BUY


After two years long bull run in pharmaceutical sector, it is not very easy to find stocks at reasonable valuation from this sector based on their past  financial performance.But based on the future growth potential ,still there is few pharma companies overlooked my market participants are available.This week let us look into one such company – SMS Pharmaceuticals.


                                                                                 This Hyderabad based API manufacturer and Contract Research and Manufacturing (CRAM) service provider came out with an IPO in 2007 @ a price of Rs.380 .Even this company went to public only few years back,promoters having vast experience in this field and most of the key persons behind this company was once  associated with  Cheminor Drugs . (An old time favorite pharma company in listed space promoted by Dr.Reddy's Lab which  later merged with Dr.Reddy’s Lab itself ). CMD and Joint MD of SMS were the key executives  in  the R&D division of Cheminor Drugs .SMS  mainly in the production of  Ranitidine HCl, Sumatriptan Succinate, Sildenofil Citrate, Omeprazole Magnesium, Ramipril, Almotriptan maleate, Gemcitabine HCl, Imatinib Mesilate and their intermediates. In addition to this about 20 products are in pipeline which either came out of patent recently or to be be come out in near future . Company have six manufacturing facilities located at Jeedimetla(two units) Bollaram ,Bachupally ,Kandivalsa and Khazippally and two  R &D facilities  at Gagillapur and Hyderabad  –all in AP.Two of its manufacturing facilities  are USFDA approved sites .At a time of stringent scrutiny process of US regulator and in the background of recent incident of loss of USFDA approval even for some big pharma companies ,SMS’s these two USFDA approved facilities are really an important asset for the company.In addition to USFDA ,its production sites are approved by other regulators from Japan,Germany and other European countries .Company exporting products to more than 70 countries across the glob and more than 50 % of income is coming through exports.SMS  is the larget producer of Ranitidine HCl in the World.


Recent Developments and Financials


Earlier in 2012-13 company sold one unit to Mylan Pharma for Rs.170 Cr .Using  this fund , company paid back part of its debt and an amount of Rs.46.5 Cr spend for buying  back of its own shares .SMS bought back  15 lakhs shares at an average price of Rs.262 . Balance of funds utilized for the upgradation  and expansion of its other facilities and for working capital requirements.Now post  completion of expansion ,company started to deliver good performance .In the latest December quarter SMS reported a jump of 100 % in top line to Rs.138 Cr and a profit of Rs.8.40 Cr against a loss of Rs.17 Cr.For the Nine month ended December SMS reported a topline of Rs.355 Cr and a net profit of Rs.9.44 Cr .On an equity base of Rs.8.47 Cr ,9 month EPS is Rs 11.10 ( ln last full year , if we exclude the other income component company was in loss and its operating cash flow were negative ) .Company started to report robust performance only from second quarter of this financial year after the completion of the expansion of all its manufacturing facilities ( See table below) .

                                     Click on the image for a better view
                          ( March 13 quarter profit was due to one time income)

I expect company will start to report full potential from next financial year onwards and FY 2014-15 may end with an EPS in the range of Rs.35-40 .Since public float is low ,liquidity is less in this stock.Promoters holding close to 64 % stake (NIL pledge) and big investors including GulfPharmaceutical Industries holding another 17.5 % stake.


Stock is currently trading @ Rs.240 which is far below its IPO price of Rs.380 and below its recent buyback price of Rs.262 . Since this recommendation is based mainly on the anticipated performance in future and its low liquid nature ,it is a high risk high profit kind opportunity and recommending only to those having capacity to take such a risk @ CMP Rs.240. Stock listed in both exchanges .


Link to company website HERE

Latest Annual Report HERE

Disc: It is safe to assume that I have vested interest in all stocks I am recommending.


Tuesday, February 25, 2014

LA-OPALA RG ,CENTUM ELECTRONICS - UPDATE


LA-OPALA RG

La- Opala RG  initially recommended @ Rs.66 ( Old posting HERE)  hits its life time high today  @ Rs.734. Company now planning a 7 % hike in its most popular DIVA range  products and giving priority to become a debt free company in near future.Company also planning for another capacity expansion, to be completed in 2015 .Even if this stock already turned as a 10 bagger ,still recommending to HOLD it for long term.

CENTUM ELECTRONICS

Centum Electronics  initially recommended @ Rs.88 ( Old posting HERE)  hits its52 week high today  @ Rs.185 .Still recommending to HOLD the stock.

Saturday, February 22, 2014

CRAVATEX LTD - BUY


------------------------------------------------------------------------------------------------------------------------------


-----------------------------------------------------------------------------------------------------------------------------


  --------------------------------------------------------------------------------------------------------------
Companies owned Indian franchise of reputed international consumer brands commanding premium valuations in Indian Stock Market .Page Industries and Jubilant Foodworks are best examples for this trend which owns the Indian rights of JOCKEY and DOMINOS PIZZA. This week let us look into another stock which can be classified in this category- Cravatex. This BSE listed micro cap owns the Indian marketing rights of more than one established International brands in India

# Company owns the long term exclusive rights to market famous Italian  sportswear brand FILA in India Sri Lanka, Nepal, Bhutan , Pakistan,Middle East and North Africa.This reputed international brand claiming 5 % market share in 2000 cr sportswear market in India which is growing 12-15 % per annum . Currently company is operating mainly through shop-in-shop formats and retail stores .Cravatex renewed exclusive license for another 30 years in 2012 for selling FILA brand in India  .After signing this long term agreement now company is planning aggressive expansion and as part of this it will add more than 60 exclusive stores in next two years to reach its number 100 .Company targeting a market share of 10 % by end of 2015 by this expansion and other marketing efforts.Company selling footwear and apparels under FILA brand in  India.

# Another international brand brought by Cravatex into India is ‘Wilson’ .Company tied up with Amer Sports (Finland) for exclusive distribution rights for the ‘Wilson’ sport  equipments which includes balls and other equipments for Tennis,Golf,Basket Ball ,Badminton,Squash..etc.


#  The most successful association ( FILA  business is  just developing) of Cravatex is with Johnson Health Tech  which is the third largest fitness company in the world.Company having exclusive license to use the brands of Johnson  Health Tech for various types of fitness equipments  like Treadmills,Cycles and various types of strength exercise equipments.There products are selling under brands like ‘Horizon’,Magnum ,Matrix,Johnson..etc. .Cavatex  is the market leader in fitness equipments through its ‘Proline’ brand fitness equipment shops with more than 50 exclusive show rooms.It is planning to add another 50 stores in next two years . Company having strong relations with well known heath club chains like Gold Gym ,Talwalkers ..etc for supplying most modern fitness equipments. Company also offering services for establishing Gyms on a turnkey basis. Company is now aggressive in tapping the vast potential of fitness equipments to be used in home.

In addition to these licensing agreement with world renowned brands ,company’s UK based  100 % subsidiary BB UK owns the rights to design ,source and supply  FILA products to Europe, United Kingdom, and Ireland.


Financials

Past five year financial performance is summarized in the below table.


Conclusion


In recent years ,company’s performance affected due to recessionary conditions  both in India and abroad.On a stand alone basis ,for the nine months of this year company reported a net profit of Rs.3 Cr and an EPS of Rs.11 .Consolidated figures will be available on completion of full year. In the past 3 years company’s stock price corrected from a level of Rs.800.Low liquidity may be a reason for this sharp fall. All these businesses having good potential and enjoys some sort of niche positioning .Considering the growth of life style diseases among Indian youth ,potential for fitness equipments business is very large especially in home segment.Company is all set to tap this vast potential and enjoying the peer company status with good sales and service network across the country.Revival in western economies and a possible peaking out of interest rate in our country are expected to change the demand scenario of company’s products.Recent renewal of licensing agreement with long tenure ( for FILA brand) will help the company to take aggressive expansion and marketing efforts. In the past two years , time was very challenging for the company due to lower disposable income of people . But from  investor's perspective ,this temporary blip is an opportunity to get into quality low liquid stocks at attractive valuation with a long term view .As I mentioned above ,low liquidity may be a reason for sharp fall in share price from higher level but the same low liquidity may push this stock to unexpected higher  levels once the situation improves.Latest December quarter result showing some early signs of improvement and ,for those having some risk appetite ,this is the right time to enter in it @ CMP of Rs 240  which is near to its three year low. ( Three year High- Low is Rs.799 - Rs.180  post bonus)

Stock listed only in BSE 

Link to Company website HERE

Link to Latest Annual Report HERE


News Related with Company Link 1 ,  Link 2 
______________________________________________________________
Since this stock is not very popular, herewith I am giving the link of one old research report on it by a broking form.( Buy recommendation initiated when its share price was  @ Rs.655) .I hope this will help you in your efforts to get a deep idea about this company .

Link HERE
_______________________________________________________________________


Disc: It is safe to assume that , I have vested interest in Cravatex

Thursday, February 20, 2014

NATH BIO-GENES INDIA LTD - UPDATE

1) While preparing the previous report on Nath Biogene , its December quarters numbers were not available. Considering the June quarter result and the general trend in seed industry ,I indicated the possibility of some loss in September and December quarter and projected an EPS of Rs.9-10 in full year FY 2013-14. Now company declared its nine month result which is far better than expected .Based on this performance revising, the expected full year EPS to Rs.12-14 .


2) Post recommendation this stock traded only on upper circuit except for a single day in BSE ie,on 14/02/2012 .On that day stock came down even near to the lower circuit. It is known from bulk deal data ,One promoter group entity bought 50000 shares on 14/02 @ Rs 66.20 from open market.( Link HERE)


Link to old posting HERE

Disc: I have vested interest in NBIL

Wednesday, February 19, 2014

BAMBINO AGRO INDUSTRIES - UPDATE


Bambino Agro Industries recommended @ Rs.40  ( Old Link HERE ) currently trading around Rs.71. This company is still one of the cheaply valued FMCG stocks with good brand.Contrary to its history ,company now reporting consistent and improving numbers for the past many quarters and came back to dividend list in 2012 after a long gap .Stock now out of Periodic Call Auction .Still recommending to HOLD for long term.

Disc: I have vested interest in Bambino

Saturday, February 15, 2014

AVANTI FEEDS - BOOK PARTIAL PROFIT

AVANTI FEEDS  recommended three times in the past -  a BUY @ Rs.68 (LINK).book profit @ Rs.150 ( LINK) and a re-entry @ Rs.109 ( LINK) .Currently stock is trading around Rs.380 ,an appreciation of about 5 times in  2 years from the initially recommended price .Company reported good result in latest December quarter .Considering the nature of business and periodically occurring uncertainties in this business (which is even beyond the control of the company) , I believe it is prudent to take out original investment  from it at current price.Recommending to Sell 1/4 of your holding  and hold the rest....

Thursday, February 13, 2014

PANACEA BIOTEC - UPDATE

Panacea Biotec recommended @ Rs.108 ( Old Posting HERE) , currently trading  @ Rs.95 .Today company reported its December quarter  numbers - excluding other income result is poor .But ,now company informed exchanges that they are going to re start supply of  pentavalent vaccine for  UNICEF projects and received order from them to supply the same for 2014-2016 period ( Read it HERE). This is very significant for the company and expecting better performance going forward .Recommending to HOLD the stock.

Wednesday, February 12, 2014

CAPLIN POINT LABORATORIES - RESULT UPDATE

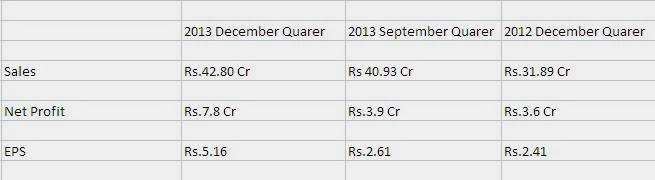
Caplin Point Laboratories recommended as a BUY @ Rs.86 ( Old posting HERE)  ,reported its December quarter result today. Company reported an increase of 30  % in sales and more than 100% jump  in net profit compared with same period of  last year.


.

 Recommending to HOLD the stock and high risk takers can consider an entry even at CMP Rs.112

Followers

Tweet TopOfBlogs